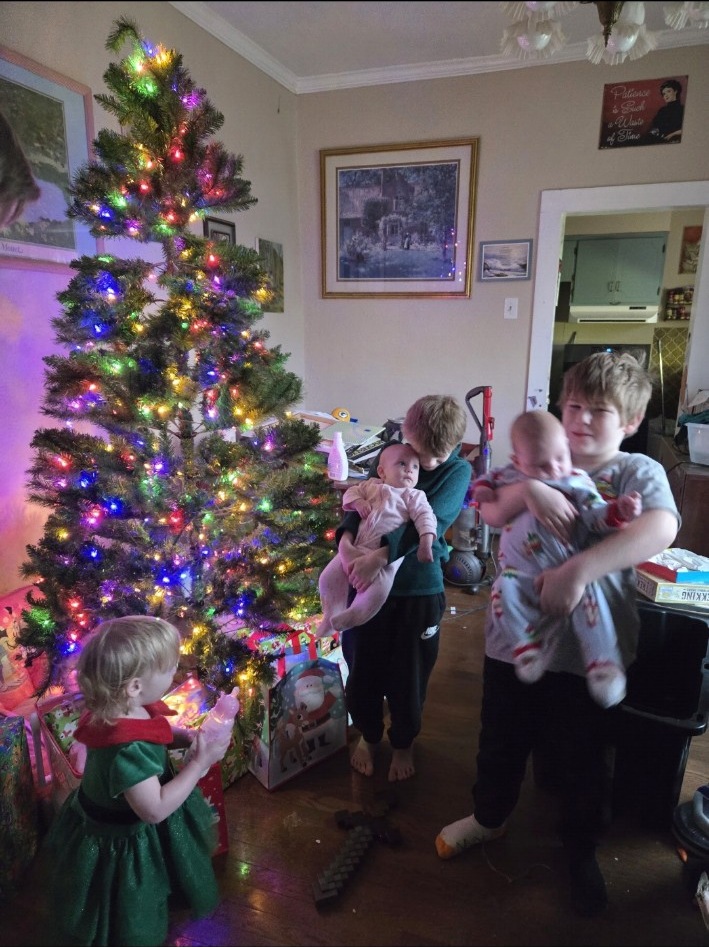
Christmas shopping for five kids is no small undertaking. And when all five are ten and under? Santa has his work cut out for him.
Normally, I start Christmas shopping over the summer. A gift here, a sale there, something hidden in a closet that I’ll probably forget about until December. Spreading it out makes Christmas a little easier on our bank account.
But not this year. Ty wasn’t working this summer, so my usual early shopping didn’t happen. Groceries, utilities, and keeping the household going had to come first. Now Christmas is approaching, and I know it’s going to be harder for us this year.
I’ve written before about how frustrating it is trying to make everyday expenses work for a family of seven. In fact, things got so ridiculous that I wrote It’s a Shame It’s Not 1800-Something — Because I’d Just Rob a Bank. 😂 The bank robbery is a joke. The financial pressure? Not so much. And Christmas doesn’t make the regular bills disappear.
I still want the magic: the excited faces, the wrapping paper, the memories. What I don’t want is to spend the first six months of 2027 paying for December 2026. So I asked someone who knows a lot more about credit than I do.
Christina Roman, Consumer Education and Advocacy Senior Manager for Experian, answered ten questions about holiday shopping, stretched budgets, credit cards, and recovering when the bills pile up. I didn’t want another lecture about cutting out a fancy coffee. I wanted answers for families who don’t have spare money in the first place.
Ten Questions for Experian’s Christina Roman
1. For families already struggling to cover necessities like housing, utilities, groceries, insurance, and transportation, how should they approach Christmas spending when there’s little or no disposable income left?
Families who are already struggling to cover necessities shouldn’t feel pressured to overspend during the holidays. The most important thing is protecting your financial stability and avoiding purchases that could create debt you’ll be dealing with well into the new year. Set a holiday budget based on what you can realistically afford, even if it’s modest. Focus on low-cost traditions, homemade gifts, or experiences that bring people together. The holidays are about connection and creating memories, not the amount spent on gifts.
Also do not overlook the value of preparing early, even if that is only a couple of months in advance. Setting aside extra money now can allow you wiggle room when the holiday season is officially here. Consider putting extra cash into a high-yield savings account, like Experian’s Smart Money™ Digital Savings Account, to potentially grow those savings more quickly.
2. When a family is living paycheck to paycheck, is there a realistic way to establish a holiday budget? Where should they begin when nearly every dollar is already accounted for?
Even when every dollar feels spoken for, creating a holiday budget can still be helpful because it forces you to make intentional decisions about spending. Start by looking for any opportunities to free up cash in your existing budget by cutting non-essential expenses. Experian has tools to help you review and cancel unused subscriptions or negotiate recurring bills, which may help create extra room for holiday spending.
If there isn’t room in the budget, it’s okay to scale back expectations. Focus on a few meaningful gifts, set spending limits with family members, or prioritize experiences and traditions over purchases. The goal isn’t to spend a certain amount, it’s to celebrate in a way that doesn’t create financial stress that follows you into the new year.
3. If a family can’t afford to pay every bill in full, how should they prioritize their financial obligations? What factors should they consider when deciding between credit card payments, utilities, housing, and other essential expenses?
If a family can’t afford to pay every bill in full, essential needs should come first. Prioritize essentials like housing, utilities, food, transportation, and insurance, since these expenses directly affect your family’s safety, stability, and ability to work and meet daily responsibilities.
Once those necessities are covered, review any remaining obligations, including credit cards and other debts. If you’re struggling to keep up, contact creditors or service providers as early as possible to ask about hardship programs, payment arrangements, or other assistance options. The earlier you communicate, the more flexibility you may have and the better positioned you’ll be to avoid additional fees, service interruptions, or long-term financial consequences.
4. What actually happens to someone’s credit when they make only the minimum payment on a credit card? Can you explain how interest, utilization, and repayment timelines affect their financial situation?
Making only the minimum payment will generally help you avoid a late payment, but it can make debt much more expensive over time. Interest continues to accrue on the remaining balance, so a larger portion of future payments may go toward interest rather than reducing the amount you owe.
It’s also important to pay attention to credit utilization, which is the percentage of your available credit you’re using. High utilization can negatively impact credit scores, even if you’re making payments on time. For consumers who are carrying balances, paying more than the minimum when possible can help reduce interest costs, lower utilization, and shorten the time it takes to become debt-free. The key is finding a payment strategy that fits your budget while steadily reducing what you owe.
5. Many consumers believe carrying a small balance on their credit cards helps build their credit score. Is there any truth to that, or is it a misconception that may actually cost families money?
This is one of the most common credit myths. Carrying a balance does not help build your credit score. In fact, it can end up costing you money because you’ll typically be charged interest on the balance you carry from month to month. What helps build credit is making payments on time, in full and keeping your credit utilization low. Ideally, you should pay your balance in full each month when possible. If you do carry a balance, the goal should be to pay it down as quickly as possible. For families trying to manage their finances, avoiding unnecessary interest charges means more money stays in their budget for other priorities.
6. If someone has multiple credit cards with outstanding balances, should they focus on paying off the smallest balance first, tackling the highest interest rate, or bringing down their overall credit utilization?
There’s no one-size-fits-all approach when it comes to paying off debt. Some people find that paying off the smallest balance first helps build confidence and momentum, while others prefer to focus on the highest-interest balance to reduce the amount they pay in interest over time. Ultimately, the most effective approach is the one that fits your budget and keeps you making consistent progress. Regular, on-time payments and a plan to gradually reduce debt can go a long way toward improving your financial health.
7. What options should families explore if they’re worried they won’t be able to make their minimum payments? Is contacting the credit card company before missing a payment genuinely helpful?
Yes, absolutely. If you’re worried you won’t be able to make a payment, it’s best to contact your credit card issuer before you miss it. Many lenders offer hardship programs, payment arrangements or other forms of assistance for customers experiencing financial difficulties.
Missing a payment can lead to late fees, increased financial stress, and potential damage to your credit if the delinquency becomes prolonged. Reaching out early gives you more options and may help you avoid some of those consequences. The most important thing is not to ignore the problem. The sooner you communicate with your lender, the more likely you are to find a manageable path forward.
8. Store credit cards frequently advertise immediate discounts during holiday shopping. What should shoppers consider before opening a new account simply to save money on Christmas purchases?
Store credit cards can seem especially appealing during the holidays when a retailer is offering an immediate discount at checkout. Before opening a new account, shoppers should look beyond the short-term savings and consider factors like the card’s interest rate, fees and whether they’ll realistically use the card after the holiday season.
Before applying, it’s a good idea to compare your options and choose a card that fits your overall financial situation and goals. Tools like Experian’s credit card marketplace can help you explore personalized card options and make a more informed decision rather than applying for a store card on impulse.
9. For someone who enters January with more debt than they anticipated, what are the first three steps you’d recommend to regain control of their finances?
First, take a deep breath and get a clear picture of what you owe. Review your balances, interest rates, and minimum payments so you can understand exactly where you stand and create a realistic repayment plan. Additionally, make sure to check your credit report and credit score so you have a complete picture of your finances. You can check yours for free at http://www.Experian.com.
Next, focus on making consistent, on-time payments and avoid adding new debt whenever possible. Even small amounts above the minimum payment can help reduce interest costs and accelerate progress.
Lastly, look for opportunities to free up cash in your budget. This could mean temporarily cutting discretionary spending, canceling unused subscriptions, negotiating recurring bills, or directing extra income, such as a tax refund or bonus, toward debt repayment.
The key is to take action early. A clear plan and steady progress can help you regain control and start the new year on stronger financial footing.
10. If a person’s credit score has already suffered because of missed payments or high balances, what realistic steps can they take to begin rebuilding it? How long might meaningful improvement take?
Rebuilding credit takes time, but it is absolutely possible. The most important steps are making all payments on time, bringing down outstanding balances, and avoiding taking on more debt than you can comfortably manage. Payment history and credit utilization are the two biggest factors that influence credit scores, so focusing on those areas can have a big impact over time. While some people may see improvements within a few months, significant rebuilding often takes longer, especially if there have been missed payments or other serious credit issues. The good news is that positive financial habits practiced consistently over time can help strengthen your credit and overall financial health.
Christmas Magic Doesn’t Have to Come With a January Bill
I’m still figuring out what Christmas looks like for our family this year. I can’t rewind the summer or magically create extra money in November. But I can remember that the things my kids will carry with them aren’t necessarily the most expensive gifts under the tree.
Maybe this year looks a little different. Maybe we do less shopping and more of the things that make Christmas feel like Christmas. I want the memories without the financial hangover.
A heartfelt thank-you to Christina Roman and Experian for taking the time to answer these questions for In My Mom Era readers. You can learn more about Christina and her work in financial education through her Experian Global News Blog author profile.
And a special thank-you to Lauren Faulconer at Pitch Public Relations for introducing me to Christina and helping make this interview possible. I truly appreciate the connection!
Find Experian on social media: Instagram: @Experian and Facebook: @Experian.
May your Christmas be merry, your memories priceless, and your January credit card statement pleasantly boring. 🎄💳
Enjoying In My Mom Era? If you believe Christmas memories should last longer than the credit-card bills, subscribe to In My Mom Era for more real-life money conversations, motherhood, and little moments of magic. 🎄❤️
With love, laughter, and a few too many open tabs,
Kelly, I’M ME ❤️


Leave a Reply