I’ve come to the conclusion that my husband and I were born in the wrong century.
Not because I particularly want to churn my own butter, die of dysentery, or give birth to five children without an epidural.
Absolutely fucking not.
But because somewhere around 1878, when shit got rough, I feel like we could’ve just saddled up a couple of horses, ridden into town, robbed a bank, and disappeared into the sunset.
Problem solved.
Of course, there’s the small issue of getting shot, arrested, or hanged. And knowing our luck, the damn horses would probably break down halfway through the getaway.
But still.
Have you SEEN the price of groceries lately?
My husband and I were discussing our finances the other day. I don’t remember exactly how the conversation started, but I suspect it had something to do with his most recent paycheck being around $500.
Five hundred dollars.
In 2026.
For a family of seven.
Somewhere in the middle of discussing how the hell we’re supposed to survive on that, my husband announced that if he could go back to the 1800s, he’d just rob a bank.
And you know what?
I understood the appeal.
Because when you’re trying to figure out how to make $500 cover $1,500 worth of expenses, the idea of riding off into the sunset with a bag of cash starts sounding rather charming.
Not that I’m advocating bank robbery.
I’m just saying I understand why the Wild West had a certain appeal.
The American Dream Has Apparently Been Discontinued
Growing up, I was taught that if you worked hard, did your job, and were a generally responsible human being, you’d be okay.
Maybe not wealthy.
Maybe not lounging on a yacht somewhere in the Mediterranean.
But okay.
You’d have a house, food, a vehicle, and hopefully a little money left over to enjoy life.
Apparently, we forgot to read the fine print.
Because here we are, two adults who have spent their lives working, raising five children, and doing our best to navigate adulthood, wondering how the hell we’re supposed to afford the basic necessities.
I spent approximately 20 years working in corporate America.
Twenty. Fucking. Years.
And when my employment ended earlier this year, I wasn’t devastated.
I ASKED for it.
I was done.
Done with the corporate bullshit. Done with the working conditions. Done with feeling like my entire life revolved around a job.
I still feel terrible for some of my friends who are stuck dealing with the nonsense I left behind.
But do I regret leaving?
No.
Not even a little.
I received a severance package, which has helped keep us afloat while we figured out our next chapter.
The problem?
Severance doesn’t last forever.
And that clock is ticking.
My Husband Lives in a Semi. Where’s the Money?
My husband became an over-the-road truck driver earlier this year.
If you’ve ever looked at trucking job advertisements, you’ve probably seen some pretty appealing numbers.
$1,500 a week!
Great pay! Excellent opportunities!
And when you’re raising five kids, those numbers look pretty damn good.
That’s what we were hoping for.
The reality?
On a GOOD week, my husband brings home around $1,000 to $1,100.
And by good, I mean that has happened maybe three times over the last few months.
Most weeks, we’re looking at something closer to $800.
And occasionally?
Five hundred fucking dollars.
Meanwhile, he’s away from home, living in a truck, missing time with his children and his wife, and working to provide for his family.
That’s an enormous sacrifice.
And what exactly are we getting in return?
Financial anxiety with a side of loneliness?
Wonderful.
Sign me up.
Now, don’t misunderstand me. I appreciate everything my husband is doing.
But I think it’s perfectly reasonable to expect that someone spending so much time away from their family should be able to make enough money to support that family.
Is that really asking too much?
Four Hundred Dollars for WHAT?!
Let’s talk about groceries.
Because this is where I start contemplating horse ownership.
We’re a family of seven, including five children ranging from toddlers to a ten-year-old.
We don’t eat particularly extravagant meals.
Quite the opposite, actually.
Our grocery list generally consists of an absolutely ridiculous amount of milk and juice, ramen noodles, pasta and sauce, cereal, Pop-Tarts, Lunchables, and whatever snacks we can afford for school lunches.
That’s pretty much it.
We’re not wandering the aisles filling our carts with steaks, fresh seafood, expensive cheeses, and gourmet ingredients.
Hell, we’re barely buying actual meals.
And I’m not particularly proud of that.
I would LOVE to fill our refrigerator with fresh fruits, vegetables, meat, and everything else that makes up a nutritious, well-balanced diet.
But right now?
We’re buying what we can afford.
Thank God for vitamins, I guess.
And then we have to add all the non-food necessities.
Diapers.
GOD. THE DIAPERS.
Wipes.
Dog food.
Laundry detergent.
Dishwasher detergent.
Toilet paper.
All those little things you don’t necessarily think about until you’re standing in Walmart wondering how the hell your total got so high.
And just to show you what I mean, on November 5 I placed a Walmart delivery order for twelve items. Not twelve different Thanksgiving dishes. Not a week’s worth of meals. Twelve things, mostly to cover school lunches.
Six Lunchables alone were $27.72. I added two frozen pizzas, two boxes of peanut butter wafers, Pop-Tarts, and a three-pound bag of apples. A few basic things to keep the kids fed.
The subtotal? $51.56. After tax and the driver’s tip, the total was $60.59.
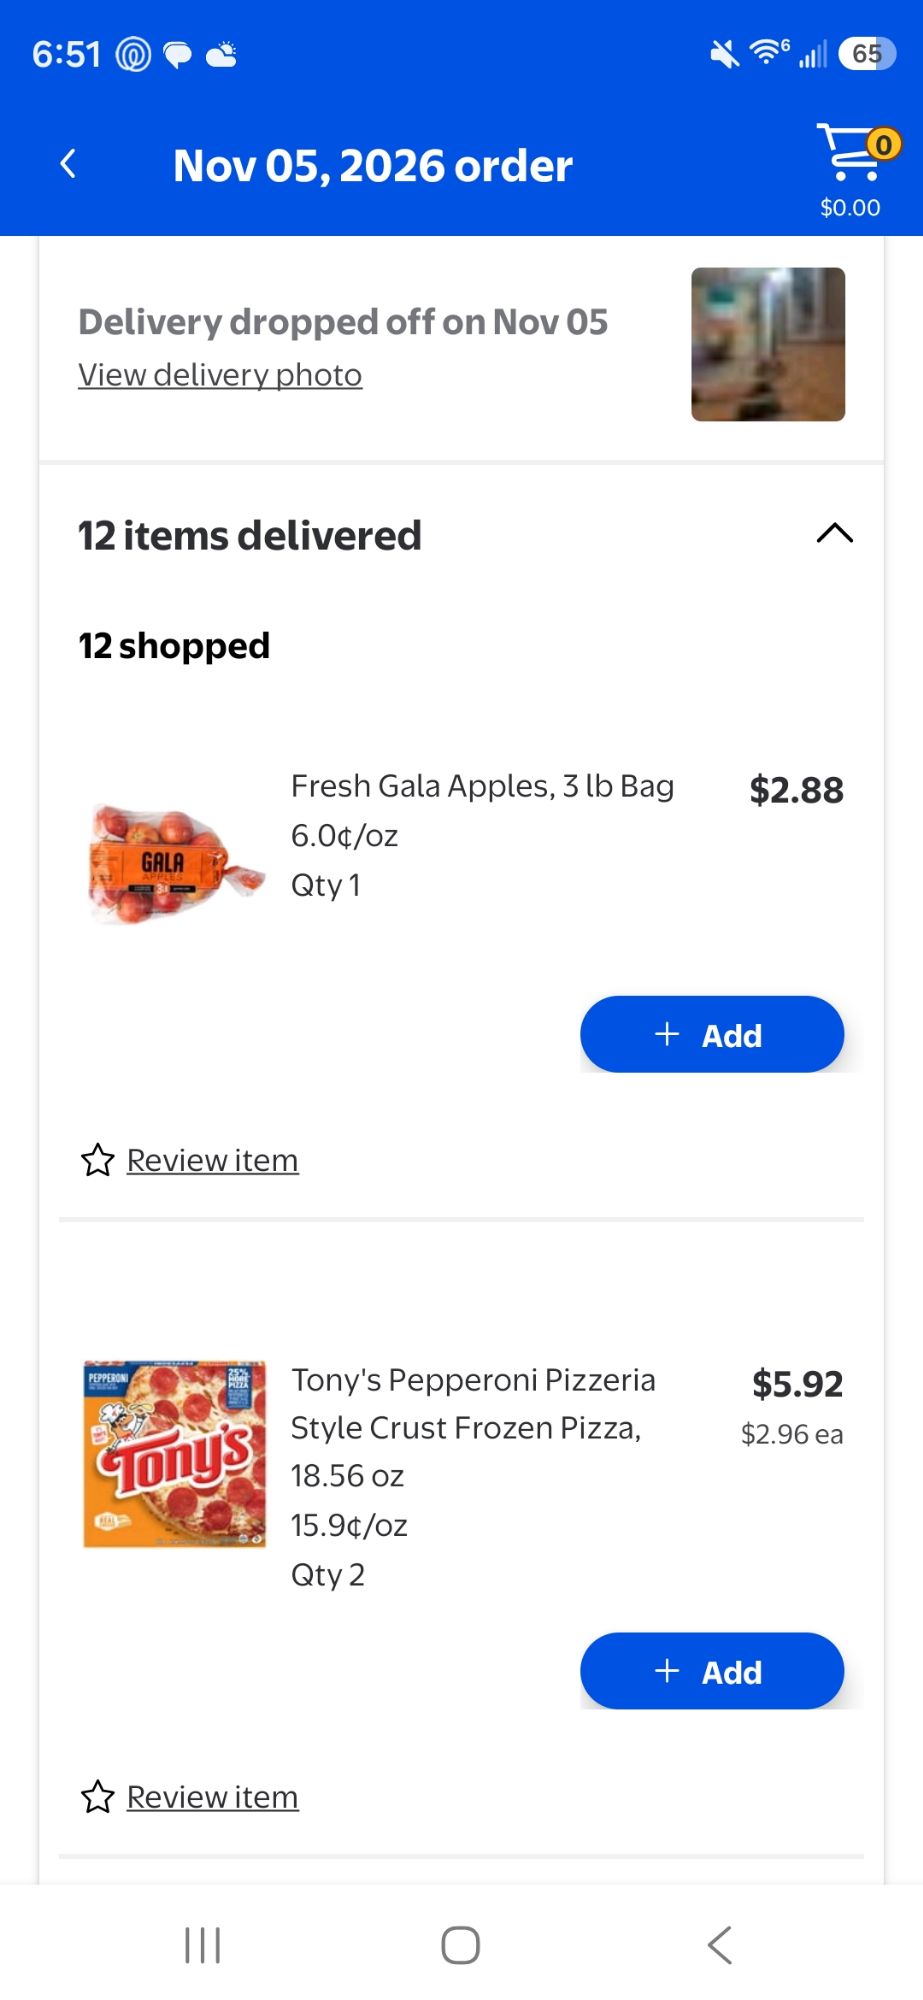
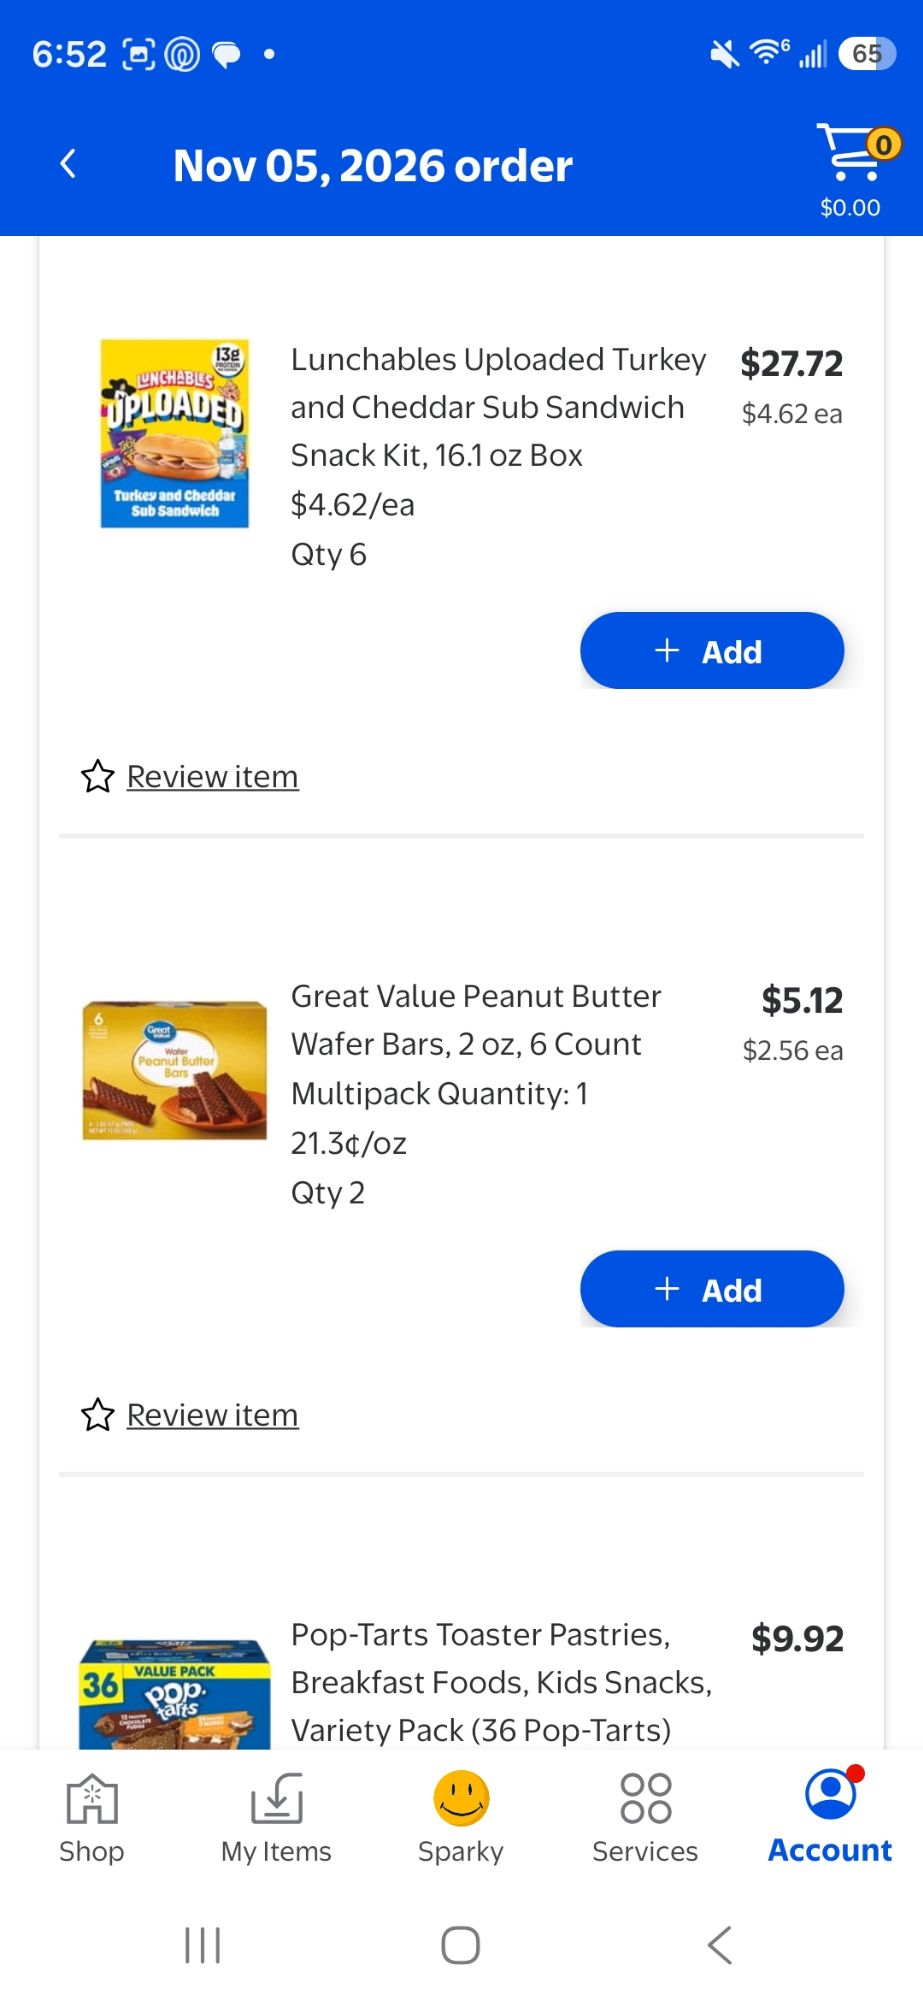
SIXTY DOLLARS. FOR TWELVE ITEMS. JUST TO HELP COVER SCHOOL LUNCHES.
And that’s a separate little order, not the $400 household shopping trip. It doesn’t even begin to solve the problem of what seven people are eating for dinner.
And suddenly?
Four hundred dollars.
FOUR. HUNDRED. DOLLARS.
For half a cart of groceries and household essentials.
Not a month’s worth of food.
Not even a particularly impressive amount of food.
Just the basics.
And remember that $500 paycheck?
Yeah.
The math doesn’t fucking math.
Maybe the Amish Are Onto Something
We live in Missouri, where gas around us has recently been running approximately $3.50 to $4.50 a gallon, depending on where we’re filling up.
We have a Chevrolet Suburban.
Because when you have five children, a tiny economical vehicle isn’t exactly practical.
And filling that Suburban?
About $100 a week.
At least.
Our older boys take Irish dance classes in St. Louis, which means we’re making the drive at least once a week.
That trip alone eats up roughly half a tank of gas.
And yes, Irish dance costs money too.
The only reason we’re able to continue is because of a family discount, which I appreciate more than I can possibly explain.
But even with that discount, the transportation costs don’t magically disappear.
Which brings me back to the horses.
We live near an Amish community, and every so often, we’ll see a horse and buggy making its way past our house.
And I swear, every time I see one, I become a little more convinced they’re onto something.
Our local Walmart even has a hitching post!
A HITCHING POST.
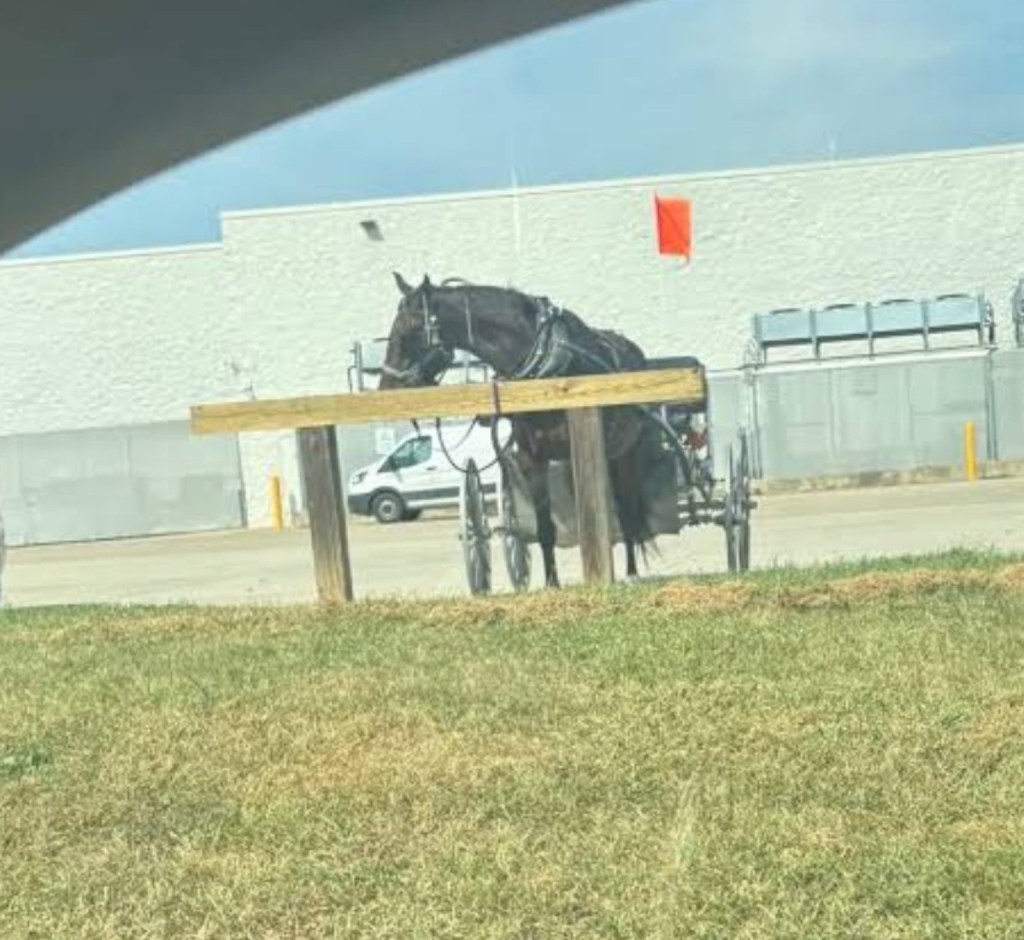
In 2026.
So now I’m seriously considering the logistics of transporting seven people by horse and buggy.
Sure, we’d need a horse. Or two.
And horse feed.
And a veterinarian.
And presumably we’d have to figure out where to park the damn things.
But no gas stations!
No $100 fill-ups!
Of course, with our luck, the horses would develop some rare medical condition requiring $4,000 in veterinary care.
And then we’d be right back where we started.
Except now we’d have two horses to feed.
Let’s Do Some Math. I Promise It’ll Be Depressing.
Let’s pretend we’re having one of those $800 paycheck weeks.
That’s $800 coming into our household.
Now let’s subtract:
- Groceries and household necessities: $400.
- Gas for the Suburban: approximately $100.
- Electricity: at least $200 a month.
- Gas utility: roughly $75 a month.
- Cell phones: approximately $120 a month.
- Our children’s school tuition: about $5,000 a year.
And we haven’t even touched vehicle insurance, additional school expenses, medical bills, emergencies, or any of the approximately 9,000 other things that cost money.
Those bills don’t all arrive on the same day, of course, but they certainly add up over the month.
At $800 a week, we’re talking about approximately $3,467 a month before accounting for any variations in income.
Our groceries and weekly gas expenses alone could eat up roughly $2,167 of that.
And that’s before utilities, tuition, or anything else.
Then throw in a $500 paycheck instead of an $800 paycheck, and suddenly the situation gets even more ridiculous.
So when people tell me we just need to budget better?
WHAT, EXACTLY, WOULD YOU LIKE ME TO REMOVE?
The diapers?
The electricity?
The food?
Maybe we should stop drinking water. I hear dehydration is free.
Oh, and Apparently Children Cost Money
Who knew?!
We have five children, and I absolutely adore them.
They’re the greatest things I’ve ever done.
They’re also financially exhausting little creatures.
School tuition alone runs around $5,000 a year.
And before someone suggests public school, let me be perfectly clear: I LOVE the school our children attend.
I love the environment, the education, and the community.
I want them to stay there.
I just wish we were in a better financial position to afford it.
And tuition is only the beginning.
School lunches.
Birthday parties.
School events.
Sports.
Activity fees.
Shoes.
Clothing.
Haircuts.
And everything else that comes with raising children who apparently insist on growing.
The audacity.
Don’t even get me started on how quickly children destroy or outgrow shoes.
You buy a brand-new pair, blink twice, and suddenly someone’s toes are trying to escape.
And when you’re buying for FIVE children?
Well.
Maybe that bank robbery isn’t sounding quite so ridiculous after all.
“Just Get Another Job!”
OH, GOOD.
WHY DIDN’T I THINK OF THAT?!
If I had a dollar for every time someone suggested I just go back to work, I might actually be able to afford groceries.
And here’s the thing.
I have 20 years of corporate experience.
I’m good at what I do.
I have skills, knowledge, and experience that could absolutely translate into another position.
Maybe I could find a job fairly easily.
But there’s something a lot of people don’t know.
Over the summer, I was diagnosed with axial spondyloarthritis.
It’s a chronic inflammatory autoimmune-related disease that affects the spine and other parts of the body.
And it has changed my life.
I’m in pain frequently.
I’m stiff.
I’m exhausted.
And I don’t mean the kind of tired that comes from raising five children.
Although, believe me, that particular brand of exhaustion is no joke either.
I mean the kind of fatigue that has me taking three-hour naps in the middle of the day just to make it through the evening.
The kind of exhaustion that doesn’t necessarily improve because you got a decent night’s sleep.
The kind that makes ordinary everyday tasks feel monumental.
So no.
The idea of jumping back into a 40- or 50-hour workweek in corporate hell isn’t particularly appealing.
And frankly?
I don’t want to.
I spent 20 years being a consistent financial provider for our household.
Twenty years of going to work, doing my job, and contributing.
And without going into every detail of our marriage and finances, I think I’ve earned the opportunity to take a different role for a while.
It’s my husband’s turn to carry more of that financial responsibility.
And before anyone comes at me, this isn’t about gender roles.
This is about OUR marriage.
OUR family.
OUR decisions.
I want to be home with my children.
I want to manage our household.
I want to have the flexibility to take care of my health without having to worry about attendance policies and corporate expectations.
And I don’t think I should have to apologize for wanting that.
Have We Made Stupid Financial Decisions? Absolutely.
Now, I don’t want anyone reading this and assuming that my husband and I have been financial geniuses who have never made a questionable decision.
Because LOL.
No.
We’ve absolutely made mistakes.
Some of them are still following us around.
For example, this summer I was sued over a loan I took out back in 2014.
TWENTY FOURTEEN.
Twelve years ago!
And what was the loan for?
Helping pay for our wedding.
Ah, romance.
Nothing says happily ever after quite like getting served court papers more than a decade after saying “I do.”
When those papers arrived, I wanted the floor to open up and swallow me whole.
I was embarrassed.
Ashamed.
And scared.
Because here’s something people don’t always talk about when they discuss financial struggles.
It’s not just about the money.
It’s about the humiliation.
The shame.
The feeling that everyone is going to judge you for circumstances they may not fully understand.
And yes, I took out the loan.
I made that decision.
I accept that.
But twelve years later, with five children, medical issues, and an already strained household budget, being faced with another financial obligation felt overwhelming.
The amount being sought would add approximately $400 a month to a budget that already isn’t working.
Four hundred dollars.
That’s another entire grocery trip.
That’s diapers, milk, cereal, and food for my children.
And that’s the part of debt that feels so vicious.
When you don’t have enough money to begin with, every additional expense makes it harder to climb out.
I’m not asking anyone to pretend that borrowing money doesn’t come with an obligation to repay it.
I’m asking how families are supposed to find their way back to financial stability when the numbers simply don’t allow any room to breathe.
Because I certainly haven’t figured that one out.
I Don’t Want to Be Rich. I Want to Be Home.
So where does all of this leave us?
Well, my severance is still helping us stay afloat.
Barely.
We’re treading water.
But eventually that money is going to run out, and unless something changes, we’re going to have some very difficult decisions to make.
Which is part of why I’ve been pouring so much time and energy into this blog.
In My Mom Era isn’t just a hobby for me.
I genuinely love writing.
I love sharing stories, reviewing books, interviewing interesting people, exploring new places, and having conversations with people I otherwise might never have met.
And I’m hoping, eventually, that this little corner of the internet can become a source of income.
Something I can build from home.
Something that allows me to work around my health.
Something that gives me the flexibility to be present for my children while contributing financially to our household.
That’s the dream.
Not a mansion.
Not a private jet.
Not a closet full of designer handbags.
Although, let’s be real, I wouldn’t necessarily turn down a winning lottery ticket.
I want to be here.
I want to be the one picking up my children from school.
I want to attend their activities.
I want to hear about their days.
I want to be available when someone is sick, upset, excited, or just needs Mom.
I want my husband to be able to spend more time at home, too.
I want to continue taking our family on adventures, because experiencing the world together matters to me.
I want to read my books.
I want to write.
I want to LIVE.
But above all else?
I want to be here with my babies.
That’s what matters most.
And if you’re reading this and enjoy what I’m building here, I’d genuinely appreciate your support.
Read my articles.
Share them.
Tell your friends.
Follow along.
Help me get this little blog in front of people who might enjoy it.
Because while I can’t promise I’ll ever become rich doing this, I can promise that I’m working my ass off trying to make it into something meaningful.
And hopefully profitable.
Because, again, have you SEEN the price of milk?!
Gratitude Doesn’t Pay the Electric Bill
I know there are people who have it worse than we do.
I’m painfully aware of that.
And I know there are people who will read this and immediately start listing all the things we could do differently.
That’s fine.
You’re entitled to your opinion.
But I’m also entitled to be frustrated.
I’m allowed to be grateful for my husband and still wish his job paid better.
I’m allowed to love our children’s school and still hate how much everything costs.
I’m allowed to appreciate the severance I received and still be terrified of what happens when it runs out.
I’m allowed to love my life and still be angry about how difficult it has become to afford that life.
Those things aren’t mutually exclusive.
And I’m tired of the idea that struggling financially means you’ve somehow failed as an adult.
I’m tired of hearing that everyone just needs to work harder.
I’m tired of being told to budget better when we’re already trying to stretch every dollar.
And I’m especially tired of the expectation that we should all just smile, be grateful, and pretend everything is okay.
Because sometimes?
Everything isn’t okay.
Sometimes life is fucking hard.
And admitting that shouldn’t be shameful.
So, About That Bank Robbery…
Look.
Obviously, my husband and I aren’t going to rob a bank.
For starters, we’d have to figure out who’s watching the five kids.
And I can only imagine how that conversation would go.
“Hey, can you watch the children for a few hours? We’re going to commit a felony.”
Probably wouldn’t go over particularly well.
And honestly, knowing our luck, we’d get caught before we even made it out of the parking lot.
But there’s a reason that ridiculous conversation about nineteenth-century bank robbers stuck with me.
Because sometimes, when you’re staring at a pile of bills, a grocery receipt that makes you want to cry, and a paycheck that doesn’t come close to covering either one, all you can do is laugh.
Otherwise, you might fall apart.
We’re going to keep trying.
My husband is going to keep working.
I’m going to keep writing.
We’re going to keep raising our children, paying what we can, and doing our best to figure out what comes next.
And somewhere along the way, I’m hoping we’ll find a little more financial stability and a lot less anxiety.
Because I don’t think it’s unreasonable to want a life where two hardworking adults can afford to raise their children without constantly worrying about money.
Until then?
I’ll be over here researching the cost of horses.
Our Walmart already has the hitching post.
We’re halfway there.
For legal purposes, this article is satire. Neither my husband nor I have any intention of robbing a bank. Although I cannot currently rule out purchasing a horse.


Leave a Reply